Diplomacy
Arunachal’s Restless Frontier: Why the India-China Border Is Heating Up Again
By Sameer Hussain |
From a line drawn in 1914 to a standoff at Taksing in 2026, the eastern…


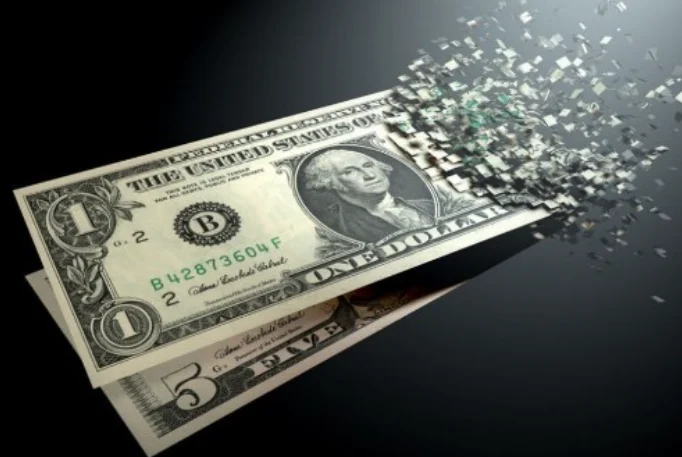
To understand why sanctions work, start with a simple fact: most global trade is priced and cleared in dollars, and almost every dollar transaction eventually passes through a bank connected to the U.S. financial system. This is what gives Washington reach far beyond its own borders. It can restrict a transaction between two other countries, say, an oil sale between Russia and a Gulf buyer, simply because the payment for that oil, at some point, touches a correspondent bank subject to U.S. law. Sanctions do not need American consent on both sides of a deal. They only need the dollar somewhere in the chain. That single fact is the foundation the rest of this argument returns to.
The events of September 2026 have sharpened, rather than started, a years-long conversation about reducing that exposure. The U.S. sanctioning of Russia’s VTB Bank over its alleged role in helping Iran evade sanctions, new legislation authorizing tariffs of up to 100% on major buyers of Russian energy, and the breakdown of UN monitoring over Iran sanctions have all reminded Moscow, Tehran and their trading partners how much leverage the dollar-clearing system hands to Washington. BRICS countries have discussed reducing dollar dependence since at least 2022, when roughly $300 billion in Russian central-bank reserves were frozen. What 2026 has done is turn that conversation from a long-term ambition into an urgent, practical one.
“Local currency trade” sounds technical, but the idea is straightforward. Instead of a Bangladeshi importer paying a Russian exporter in dollars, both sides agree to price and settle the deal in taka, roubles, or some combination of the two. This can happen through bilateral currency swap lines, where two central banks agree to exchange a set amount of each other’s currency, giving commercial banks on both sides something to work with. It can happen through direct rupee-rouble or yuan-rouble settlement arrangements. Or it can happen through local-currency invoicing, where the trade contract itself is written in a currency other than the dollar, avoiding U.S.-linked clearing systems entirely. None of this requires abolishing the dollar. It simply requires building parallel plumbing that trade can flow through instead.
This is no longer theoretical. India has settled a large share of its oil trade with Russia in rupees rather than dollars, a direct response to sanctions pressure on the Russian banking sector. China has spent years pushing yuan internationalization, encouraging trading partners to invoice and settle in renminbi rather than dollars, particularly for energy and commodities. Russia and Iran, both heavily sanctioned, have built bilateral arrangements to keep trade moving between them without touching Western-linked banks. These are functioning, if still limited, examples of countries constructing an alternative to the system that sanctions rely on.
It is important to be precise about what this actually achieves. A transaction that never touches dollar clearing is genuinely harder for Washington to see, and therefore harder to block. That is real value. But it is not full immunity. Goods still need to be shipped, insured, and moved through ports — and much of the world’s shipping and marine insurance industry remains concentrated in Western hands. A cargo can be settled entirely in roubles and yuan and still be delayed or refused coverage if the insurer or shipping line has exposure to U.S. sanctions law. Local-currency settlement is a partial shield around the payment, not a shield around the entire trade.
The bigger constraint is scale. A currency swap line is only useful if the currency at the other end is something a bank, or the next link in a supply chain, is actually willing to hold. This is BRICS’s current weak point. The ruble and the taka are not deeply convertible currencies with liquid global markets like the dollar. A trading partner three steps down the chain may refuse a currency it cannot easily convert or trust to hold its value. Even the yuan, despite years of promotion, still accounts for a small fraction of global reserves and trade invoicing compared to the dollar. Local-currency systems work well between two committed partners with high trade volumes, like India and Russia on oil. They work far less well as a general-purpose substitute for dollar clearing across dozens of trading relationships.
For South Asia, energy trade is the clearest test case. If Bangladesh could settle a portion of its crude or LNG purchases from Gulf or Russian suppliers in taka, rupees, or a swapped currency rather than dollars, it would reduce two pressures simultaneously: exposure to sanctions-related payment disruption, and pressure on scarce dollar reserves during a crisis. India’s rupee-oil arrangement with Russia offers a working template. Bangladesh could not adopt it overnight; India’s trade volumes and negotiating weight are far larger, but it shows the mechanism is not purely hypothetical for the region.
Before opting into these arrangements, South Asian governments need to weigh real risks. Currency volatility is one: a contract settled in a partner’s currency can become more expensive if that currency depreciates sharply, as sanctioned economies’ currencies sometimes do. Shallow convertibility is another: taka or rupee balances accumulated through swap arrangements may be hard to use for anything beyond the original bilateral relationship, effectively trapping value. There is also an opportunity cost. Every transaction moved out of dollars is one that no longer builds the dollar liquidity a country needs for its other obligations, from debt service to unrelated imports. And there is a reputational risk that deserves honest attention: expanding currency arrangements with Russia or Iran, even for entirely legal and sanctions-compliant trade, can invite scrutiny from Washington and raise questions about alignment that South Asian governments may not want to answer.
None of this means South Asian countries should avoid local-currency settlement. It means they should treat it as one tool in a diversified toolkit, not a wholesale exit from the dollar system. The same logic that should guide energy suppliers, export markets and shipping routes applies here: no single payment channel should become either fully relied upon or fully avoided. A modest, carefully built local-currency channel for specific high-volume relationships, energy purchases being the obvious candidate, can reduce exposure without creating new dependencies or inviting unnecessary risk.
The dollar’s dominance in global trade is not about to end, and BRICS is not building a replacement for it. What is being built, slowly and unevenly, is a set of alternative channels that make the current sanctions regime somewhat less absolute for the countries caught in its path. For Bangladesh and its neighbors, the right response is neither to rush into these arrangements nor to ignore them. It is to understand them well enough to use them selectively, as a hedge against a system that has repeatedly shown in 2026 how quickly it can turn its leverage against bystanders.
Posted in Economy

From a line drawn in 1914 to a standoff at Taksing in 2026, the eastern…